What does cross-border payroll mean?
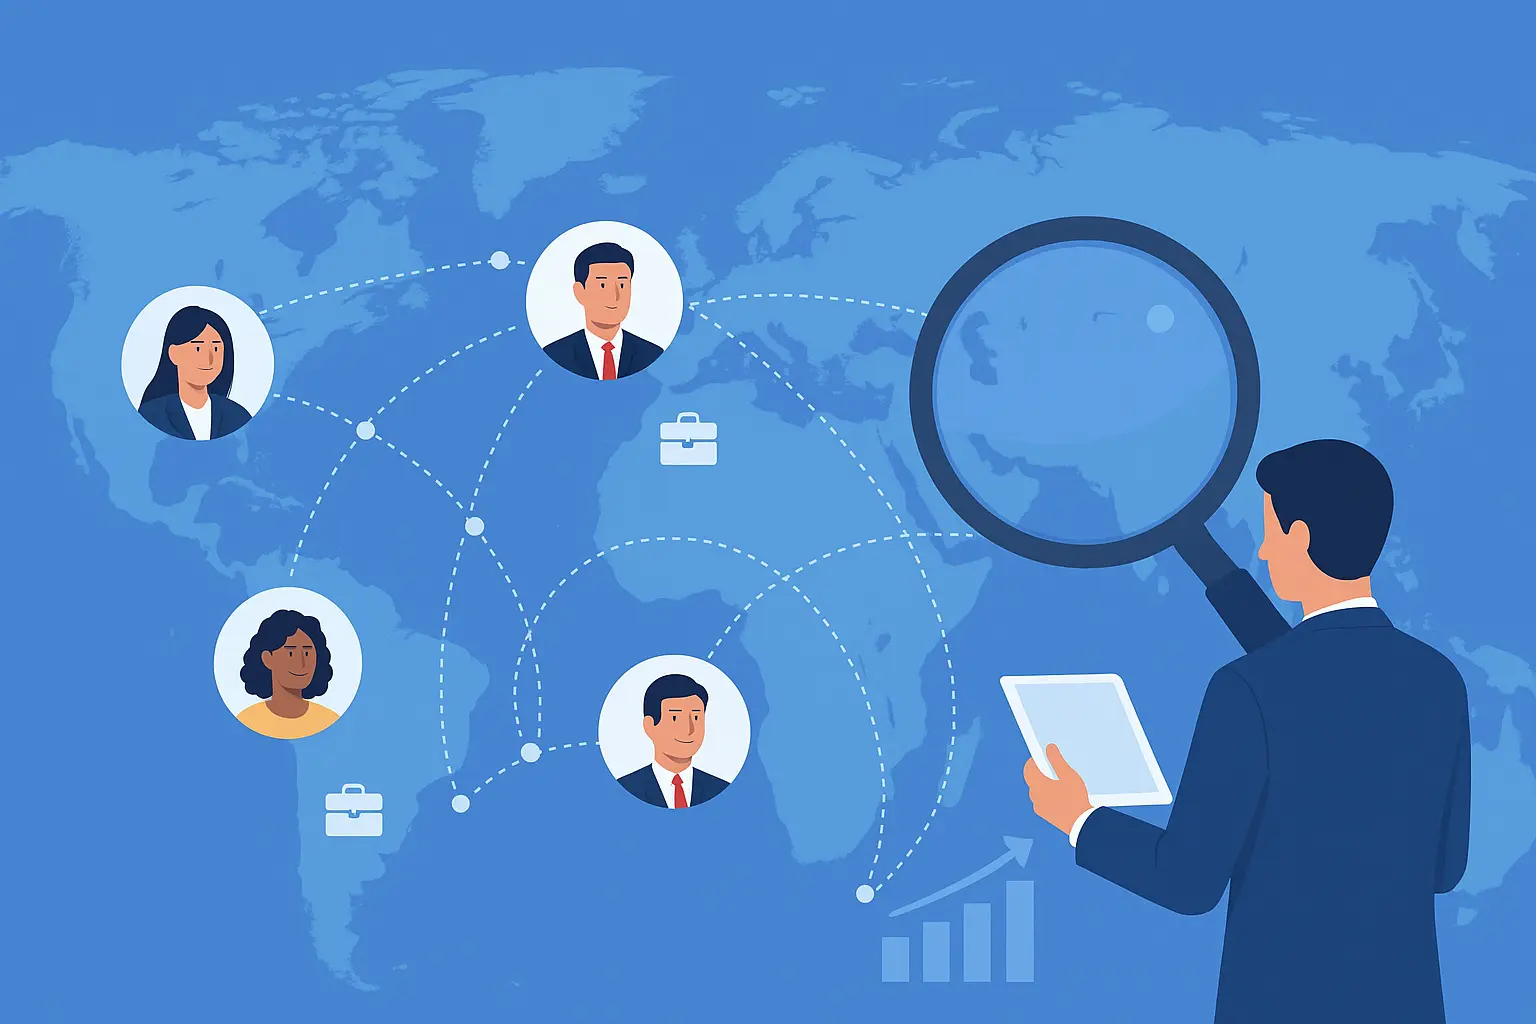
Cross-border payroll refers to payroll arrangements that involve more than one country. This may happen when a company hires remote employees overseas, manages employees across several countries, or uses an Employer of Record to employ workers in a market where the company does not have its own local entity.
For example, a company in Singapore may hire employees in Indonesia, the Philippines, Malaysia, Vietnam, and Thailand. Even if the employees report to the Singapore team, each country may have its own payroll rules, statutory contribution systems, tax processes, payslip expectations, wage payment timelines, and employment documentation requirements.
Cross-border payroll is not only about sending salary overseas. It is about making sure the employee is paid correctly under the local employment and payroll framework.
Why cross-border payroll matters for employers
Cross-border payroll matters because payroll mistakes can quickly become employee trust, compliance, and financial issues. Employees expect to be paid accurately and on time. Employers need to calculate salary, deductions, employer contributions, statutory benefits, tax-related payroll items, and final pay correctly.
For SMEs, the challenge is that payroll becomes more complex once hiring expands beyond one country. A founder or HR manager may understand monthly salary, but may not know how to account for Indonesia’s BPJS Kesehatan and BPJS Ketenagakerjaan, the Philippines’ 13th Month Pay and government contributions, Malaysia’s EPF, SOCSO, and EIS, or similar systems in Vietnam and Thailand.
This is why cross-border payroll should be planned before the employee starts work. It affects offer letters, employment contracts, onboarding, payroll calendars, cost estimates, and ongoing HR administration.
For companies hiring without a local entity, Weshine’s payroll services and Employer of Record support can help employers manage local payroll processes while maintaining clearer regional visibility.
What should cross-border payroll include?
A practical cross-border payroll process should cover more than basic salary.
Not every country uses the same payroll structure. Employers should avoid using one spreadsheet or payroll template for the whole region without checking local requirements.
Southeast Asia and cross-border hiring context
Cross-border payroll in Southeast Asia is highly country-specific. In Indonesia, payroll may involve BPJS Kesehatan, BPJS Ketenagakerjaan, PPh 21 withholding, THR, and employment contract considerations. Indonesia’s Presidential Regulation No. 64 of 2020 sets out BPJS Kesehatan contribution rules for wage-earning employees, including the 5% contribution split between employer and employee.
In the Philippines, payroll may involve SSS, PhilHealth, Pag-IBIG, withholding tax, and 13th Month Pay. PhilHealth explains employer registration for social health insurance coverage, while the Philippines’ Presidential Decree No. 851 requires covered employers to pay 13th Month Pay.
In Malaysia, payroll may involve EPF, SOCSO, EIS, monthly tax deductions, and employment records. KWSP explains that employers must pay EPF contributions by the 15th of the following wage month, while SOCSO sets out SOCSO and EIS contribution responsibilities.
Vietnam and Thailand also have their own social insurance, tax, payroll reporting, and employment requirements. The practical point is that “payroll in Southeast Asia” is not one single system. Each country needs local review.
Note: Payroll rules, statutory contribution rates, wage caps, tax treatment, filing deadlines, and reporting processes may change. Employers should verify the latest local requirements before setting up or changing payroll.
Cross-border payroll vs local payroll
Cross-border payroll and local payroll are connected, but the management problem is different.
For employers, cross-border payroll requires both local compliance and central visibility. The company needs to know that each employee is paid correctly in their country, while finance and HR still need consolidated reporting across the regional workforce.
Payroll, tax, and remote work risk
Cross-border payroll can also raise tax and business presence questions. If an employee works remotely from another country, employers may need to consider whether local payroll registration, income tax withholding, or employer reporting obligations apply.
In some cases, remote work may also create broader tax questions, including whether the company has a taxable presence in the employee’s country. The OECD has discussed how cross-border remote work can raise permanent establishment considerations depending on the facts, tax treaty position, employee role, and business activity.
This does not mean every remote hire creates the same tax result. It means payroll, tax, and employment structure should be reviewed before hiring.
Practical employer example
A Hong Kong company wants to hire one operations assistant in Indonesia and one customer support specialist in the Philippines. If the company only compares monthly salary, it may underestimate the true payroll cost.
For the Indonesian hire, the company should consider BPJS Kesehatan, BPJS Ketenagakerjaan, PPh 21 withholding, THR, leave, and local payroll administration. For the Philippines hire, it should consider 13th Month Pay, SSS, PhilHealth, Pag-IBIG, withholding tax, leave, and final pay treatment.
A better approach is to prepare a country-specific payroll cost estimate before issuing the offer. This helps HR, finance, and management understand the actual employment cost and avoid payroll surprises.
Common mistakes employers should avoid
A common mistake is assuming that paying salary from headquarters is enough. Salary transfer is only one part of payroll; statutory contributions, deductions, tax withholding, and local records may still matter.
Another mistake is using contractor payments for employee-like roles. If the worker functions like an employee, payroll and statutory benefit obligations may arise depending on local rules.
Employers should also avoid relying on one regional payroll template for every country. Payroll requirements differ across Southeast Asia, and details such as wage caps, contribution rates, filing timelines, and annual payments can change.
Finally, employers should avoid separating payroll from employment structure. The payroll setup depends on whether the worker is hired through a local entity, Employer of Record, contractor arrangement, or outsourcing model.