What does Tunjangan Hari Raya (THR) mean?
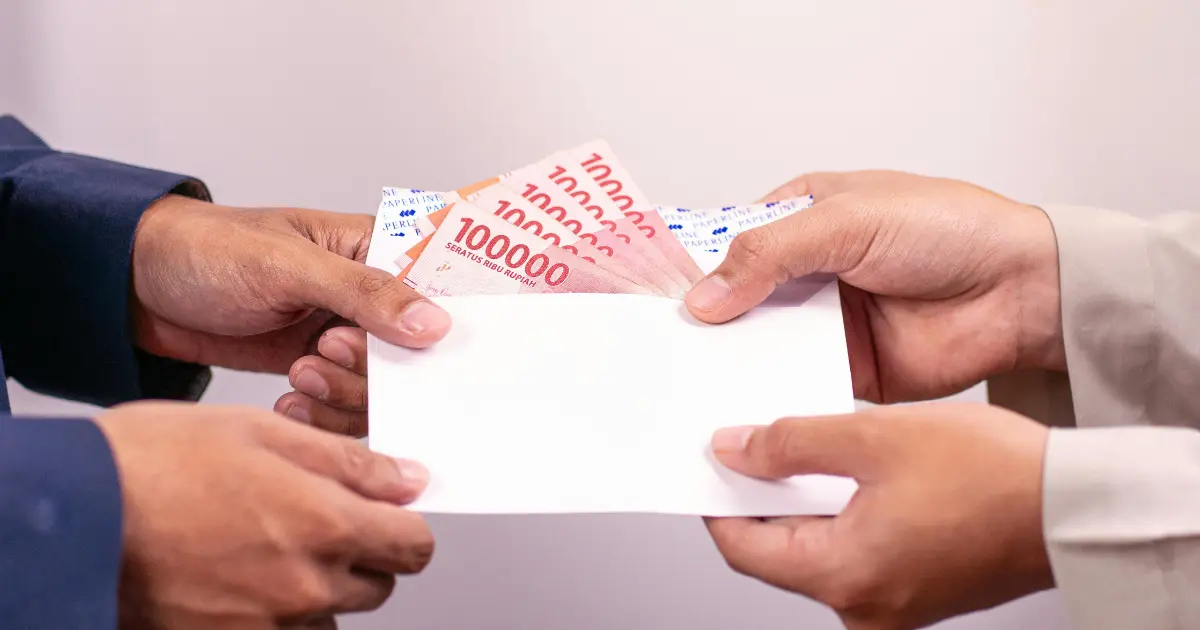
Tunjangan Hari Raya, usually shortened to THR, is a mandatory religious holiday allowance in Indonesia. It is paid to eligible employees before their religious holiday, such as Eid al-Fitr, Christmas, Nyepi, Vesak, or another recognised religious holiday based on the employee’s religion.
THR is not the same as a discretionary bonus. A discretionary bonus may depend on company performance, individual performance, management approval, or company policy. THR is a statutory employment payment under Indonesia’s manpower framework and should be planned as part of payroll cost.
Indonesia’s Ministry of Manpower Regulation No. 6 of 2016 on religious holiday allowance explains the THR framework for employees and employers. Employers should also review Indonesia’s Government Regulation No. 36 of 2021 on Wages, which recognises THR as non-wage income that employers may be required to provide.
For companies hiring Indonesian employees from overseas, the practical point is simple: THR should be included in annual employment cost planning before the offer is made, not treated as a surprise payment later.
Why THR matters in Indonesia payroll
THR matters because it creates a major annual payroll obligation. A monthly salary estimate does not show the full cost of employing someone in Indonesia if THR is excluded.
This is especially important for SMEs hiring their first employee in Indonesia. A company may agree to a monthly gross salary and budget for 12 months of payroll, but THR can effectively add another required payment depending on employee eligibility and length of service. It may also affect cash flow because payment is usually due before the employee’s religious holiday.
THR is also important for employee trust. In Indonesia, employees commonly expect THR as part of the employment relationship. Late, incorrect, or missing THR payments can create dissatisfaction and payroll disputes.
Weshine’s payroll service can support businesses that need help managing Indonesia payroll, including salary payments, statutory deductions, payslips, and annual payroll items such as THR. For companies hiring employees in Indonesia without setting up a local entity, Weshine’s Employer of Record service can support the local employment and payroll structure.
Who is eligible for THR?
Under Indonesia’s THR framework, employees with at least one month of continuous service are generally entitled to THR. This can include employees under indefinite-term contracts and fixed-term contracts, depending on the employment relationship and applicable rules.
A common misunderstanding is that THR only applies to permanent employees. Employers should be careful with this assumption. Fixed-term employees under PKWT may also be entitled to THR if they meet the service requirement.
THR entitlement should be checked based on the employee’s actual employment status, length of service, wage structure, and current Indonesia manpower guidance. If the company uses an Employer of Record, THR should be coordinated with the local legal employer and payroll team before the holiday period.
How is THR calculated?
The standard THR calculation depends on the employee’s length of continuous service.
A common prorated calculation is:
THR = length of service in months ÷ 12 × 1 month’s wage
For THR purposes, “wage” is commonly understood as basic salary plus fixed allowances. Employers should distinguish fixed allowances from variable allowances, reimbursements, bonuses, commissions, and other non-fixed payments before calculating THR.
Note: This is a simplified employer guide. THR treatment can depend on wage structure, contract terms, company policy, collective agreement, employee status, and the latest Ministry of Manpower guidance. Employers should verify current local rules before processing THR.
Simple THR calculation example
An employee in Indonesia earns IDR 10,000,000 per month in basic salary and has worked continuously for 12 months or more.
If the same employee has worked for 6 months, the prorated calculation would be:
IDR 10,000,000 × 6 ÷ 12 = IDR 5,000,000
This example assumes the monthly wage used for THR is IDR 10,000,000 and does not include variable pay or other items. The actual calculation should be checked against the employee’s wage structure and current Indonesia payroll rules.
When should THR be paid?
THR is generally paid before the employee’s religious holiday. Indonesia’s THR rules are commonly understood to require payment no later than seven days before the relevant religious holiday.
This timing matters for payroll planning. If a company hires employees in Indonesia, it should prepare cash flow and payroll approvals ahead of the holiday period. Waiting until the normal monthly payroll date may not be appropriate if the THR deadline falls earlier.
HR and finance teams should also confirm which religious holiday applies to each employee, especially in a diverse workforce. The timing of THR may differ depending on the employee’s religion and the relevant holiday.
THR and overseas companies hiring in Indonesia
A company does not avoid THR simply because it is based outside Indonesia. If the employee is locally employed in Indonesia, Indonesia payroll and employment rules may apply.
This is a common issue for businesses hiring remote employees in Indonesia. Paying a monthly salary from overseas may seem administratively simple, but the company still needs to consider employment structure, PPh 21, BPJS Kesehatan, BPJS Ketenagakerjaan, THR, payslips, leave, and termination-related obligations.
If the company does not have an Indonesian entity, it should decide the hiring structure before the employee starts. An Employer of Record can act as the local legal employer and manage payroll items such as THR under the local employment framework.
For broader planning, Weshine’s Indonesia country guide can help companies understand key employment and payroll considerations before hiring in Indonesia.
Common THR mistakes companies should avoid
A common mistake is treating THR as a discretionary bonus. THR should be planned as a statutory payroll obligation for eligible employees, not as a reward that can be removed because business performance is weaker than expected.
Another mistake is budgeting only for 12 months of salary. THR can materially change annual employment cost, especially when hiring several employees in Indonesia.
Companies should also avoid calculating THR from the wrong pay basis. Basic salary, fixed allowances, variable allowances, incentives, and reimbursements should be reviewed carefully before payroll is processed.
A final mistake is waiting until the holiday period to prepare THR. HR and payroll teams should track eligibility and service period throughout the year so the payment can be calculated accurately and paid on time.